

The health savings account is one of the more misunderstood tools in the U.S. tax code. Most people with access to one treat it as a healthcare debit card, swiping it at a pharmacy and forgetting about. In reality, the HSA is a sophisticated, multi-purpose savings vehicle with a tax structure that doesn’t exist anywhere else in federal law.
This article covers the basics: how HSAs work, who qualifies, the contribution limits for 2025 and 2026, and the mechanics of the triple tax advantage. For our Bitcoiner readers, we also have a note on Sound HSA, which is a Bitcoin-native HSA product.
Eligibility: The High Deductible Health Plan
To contribute to an HSA, an individual must be enrolled in a High-Deductible Health Plan (HDHP) for their healthcare insurance coverage. The IRS sets specific thresholds each year that determine what a HDHP is. For 2025, an HSA-qualified HDHP is defined as a plan with:
A minimum deductible of $1,650 for self-only coverage, or $3,300 for family coverage
Annual out-of-pocket maximums not exceeding $8,300 (self-only) or $16,600 (family)
Beyond the HDHP requirement, a few other disqualifiers apply. Enrollment in Medicare, either Part A or Part B, ends HSA contribution eligibility. Being claimed as a dependent on another person’s tax return also disqualifies an individual from contributing. And concurrent enrollment in most other health coverage, including a general-purpose Flexible Spending Account (FSA), typically disqualifies HSA eligibility as well. Confirm with a professional regarding specific situations.
Eligibility is determined on the first day of each month. Someone who switches from an HDHP to a non-HDHP mid-year isn’t eligible to contribute for the months they’re not covered — though the IRS’s “last-month rule” allows for some nuance when coverage exists on December 1.
A recent expansion worth noting: The One Big Beautiful Bill Act (enacted 2025) extended HSA eligibility meaningfully. Starting January 1, 2026, bronze and catastrophic plans available through an Exchange are treated as HSA-compatible HDHPs, regardless of whether they technically meet the standard HDHP definition. Direct Primary Care (DPC) service arrangements also become compatible with HSA eligibility in 2026. And the ability to receive telehealth services before meeting an HDHP deductible — without losing HSA eligibility — was made permanent.
These changes expand the eligibility pool significantly and are worth revisiting for those who previously ruled out HSA participation based on their plan type.
Contribution Limits
The IRS adjusts HSA contribution limits annually. For 2025 and 2026:
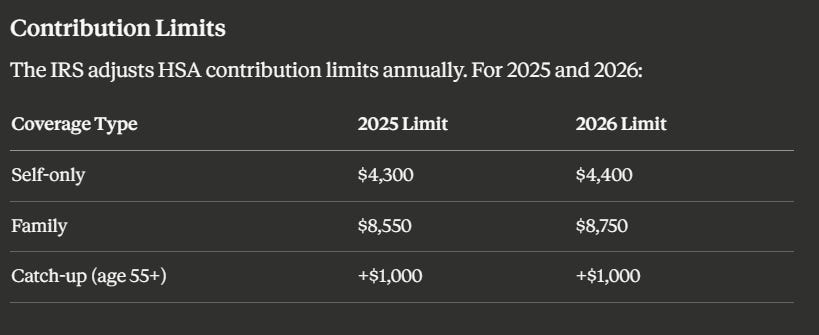
The catch-up contribution applies to individuals age 55 or older who are not yet enrolled in Medicare. Spouses who are both HSA-eligible cannot share a single account. Each must maintain separate HSAs, though under family HDHP coverage, the combined household limit applies.
Employer contributions count toward the annual limit. If an employer contributes $1,500 to an employee’s HSA under family coverage in 2025, the employee’s own contribution is capped at $7,050.
Importantly, excess contributions are subject to a 6% excise tax for each year they remain in the account, thus it is generally advisable to avoid excess contributions to an HSA. The correction, should an excess contribution occur, is to withdraw the excess (plus any earnings on it) before the tax filing deadline, including extensions.
The Triple Tax Advantage
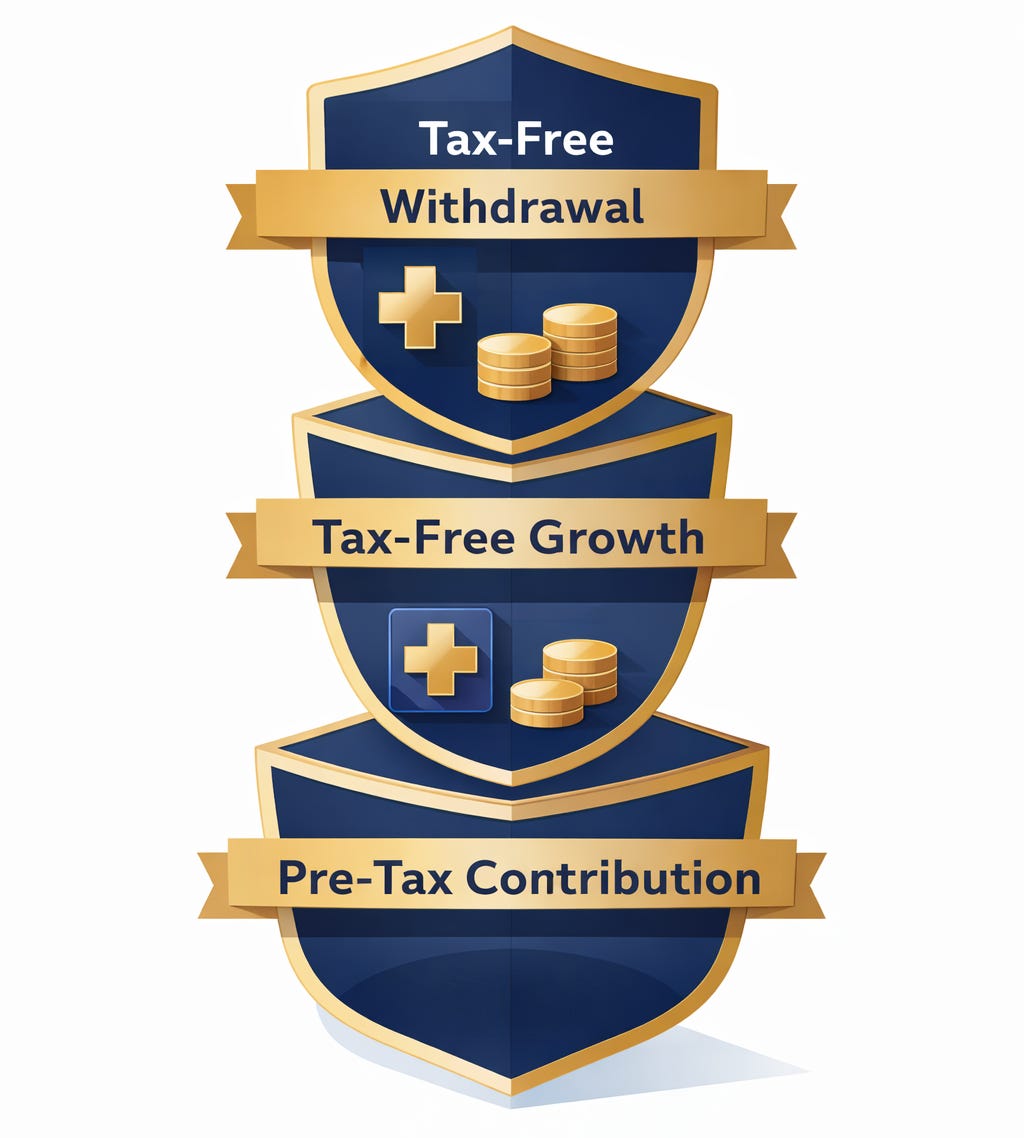
One of the more interesting realities of the HSA is that it has what many refer to as the “Triple Tax Advantage.” This works out as follows:
1. Contributions reduce taxable income
HSA contributions made through employer payroll deduction are excluded from gross income and they’re also excluded from FICA taxes (Social Security and Medicare). That’s a tax benefit that traditional IRA contributions don’t provide. Contributions made directly to an HSA outside of payroll are deductible on the federal return as an above-the-line deduction under IRC § 223, meaning no itemization is required.
2. Growth inside the account is tax-free
Funds held in an HSA can be invested. Most custodians offer mutual funds or ETFs once the account reaches a certain balance threshold (for example, $1,000). Earnings including interest, dividends, and capital gains accumulate without generating a taxable event. The growth is sheltered entirely for as long as it remains in the account.
3. Qualified distributions are tax-free
Withdrawals can be used to pay for qualified medical expenses — a broad category that includes deductibles, copays, prescriptions, dental care, vision care, and more — are excluded from gross income.
Taken together, this structure means a dollar contributed to an HSA can enter pre-tax, grow without taxation, and exit without taxation — provided it’s used for qualified medical expenses. That’s a sequence that doesn’t exist in any other account type in the U.S. tax code.
Non-medical withdrawals: Before age 65, distributions not used for qualified medical expenses are included in gross income and subject to a 20% penalty. After age 65, the 20% penalty disappears — non-medical withdrawals are taxed as ordinary income, functionally equivalent to a traditional IRA distribution.
A Note on Reimbursement Timing
One nuance that’s often overlooked is that the IRS doesn’t impose a deadline on when HSA funds must be used to reimburse a qualified medical expense; it only requires that the expense was incurred after the HSA was established. This means an account holder can pay out-of-pocket for medical expenses today, let the HSA balance compound, and reimburse themselves years later, tax-free.
The practical implication for account holders is that an HSA can be used as a long-term investment account for individuals who have the cash flow to cover current medical expenses without tapping the account. The key to all of this is keeping accurate documentation. Receipts and records of qualified expenses need to be retained, since there’s no mechanism to report them to the IRS in real time.
After 65: The HSA as a Retirement Account
Once an account holder turns 65, the 20% penalty on non-medical withdrawals drops away. At that point, the HSA essentially functions as a traditional IRA for non-medical spending. Distributions are taxable as ordinary income but still retain tax-free status for qualified medical expenses.
Given that healthcare is one of the largest line items in retirement spending (the average retired couple is projected to need over $300,000 in healthcare costs in retirement), a fully funded HSA with decades of compounding behind it can cover a substantial portion of that exposure entirely tax-free.
Sound HSA: A Bitcoin-Native Approach
Most HSA custodians offer a limited menu of investment options, including preselected money market funds, index funds, sometimes a brokerage window. For those who think about long-term purchasing power through a Bitcoin lens, that menu doesn’t often align with the investment and savings goals of Bitcoiners.
But innovation is on the way: Sound HSA is building the first Bitcoin-native HSA platform. It combines the triple tax advantage of a traditional HSA with the ability to hold bitcoin as the savings medium. The concept is direct: rather than denominating healthcare savings in a depreciating fiat instrument, Sound HSA allows account holders to accumulate bitcoin for future healthcare needs within the established HSA structure.
The platform is currently in waitlist/early launch mode. An app is live on iOS and Android, and includes a “move to earn” feature where users complete health and wellness challenges to earn satoshis. Sound HSA’s founders have framed the product as building toward a broader sovereign health platform — one that pairs sound money with healthcare savings in a way that returns financial control to the account holder.
For Bitcoiners who have thought carefully about how each dollar is saved and in what form, the HSA structure and a Bitcoin-denominated account are a logical pairing. It’s worth keeping an eye on as the product matures.
HSA Summary: The Rules at a Glance
Feel free to screenshot:
Eligibility: Enrollment in an HSA-qualified HDHP (or, starting 2026, a bronze/catastrophic Exchange plan or DPC arrangement)
Disqualifiers: Medicare enrollment, dependent status, most concurrent non-HDHP coverage
2025 limits: $4,300 self-only / $8,550 family / +$1,000 catch-up (55+)
2026 limits: $4,400 self-only / $8,750 family / +$1,000 catch-up (55+)
Contribution deadline: Tax filing deadline (typically April 15) for the prior year
Rollover: Unlimited — balances carry forward indefinitely
Qualified expenses: See IRS Publication 502
Penalty before 65: 20% on non-medical distributions, plus income tax
After 65: No penalty; non-medical distributions taxed as ordinary income
Questions about how an HSA fits into a specific situation, or how to handle HSA accounting for a Bitcoin-focused business? Reply to this email.
This content is for educational purposes only and does not constitute personalized tax, legal, or financial advice. Consult a qualified tax professional regarding your specific circumstances.