


Note: this is part 2 of a 3-part series on Bitcoin on the Balance Sheet for Business. If you haven’t read Part 1, we recommend starting there. It lays the groundwork for why companies are rethinking their treasury strategies in the face of inflation, declining purchasing power, and the promise of Bitcoin.
For those newly interested in Bitcoin, the early phases of the learning journey are wrought with a number of possible objections. And these objections are completely understandable. In fact, I, and everyone on the team here at Satoshi Pacioli, have considered each of these objections ourselves as we studied Bitcoin. They include statements like:
“Bitcoin is too volatile.”
“I’m worried about a government regulatory crackdown.”
“I’ve heard that custody is risky. Seems too techy for me.”
“What’s even the accounting standard for holding Bitcoin?”
“What about taxes? I don’t know how those work.”
“Bitcoin doesn’t produce cashflows and I can’t use it for anything.”
In this article, we’ll consider each of these objections and provide responses that address them.
“Bitcoin is too volatile.”
Initially, at face value, this observation is: Bitcoin, valued in traditional fiat currencies such as the U.S. dollar, historically is a highly volatile asset. It is not uncommon to see large price swings in relatively short amounts of time. At the time of writing this article, Bitcoin is down roughly 31% from it’s all-time high that it established just over a month ago (a move down from $126,000 to currently $87,000 as of the time of writing).
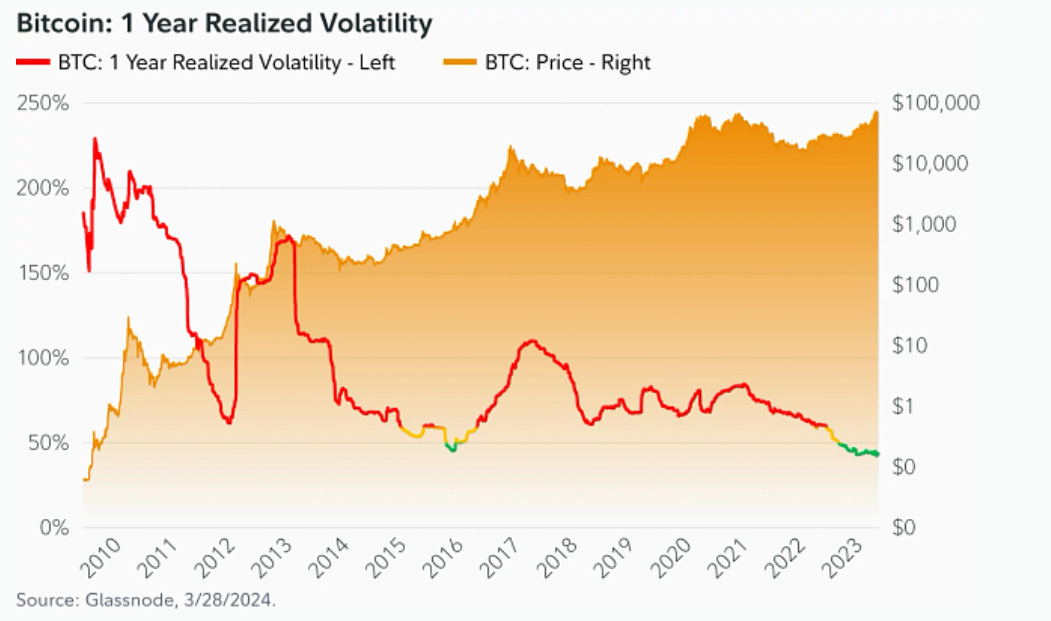
However, short-term price action aside, Bitcoin’s volatility favors its holders to the upside in the long run. According to a report published by Fidelity, Bitcoin’s CAGR from February 2020 through February 2024 (a four year period that included the Covid drawdown and the November 2022 market correction) was roughly 58% compared to the S&P 500’s at 13.6%. That same report also notes that while Bitcoin’s historical volatility has been high, as Bitcoin matures as an asset class, it’s volatility is also decreasing relative to its volatility in the past.
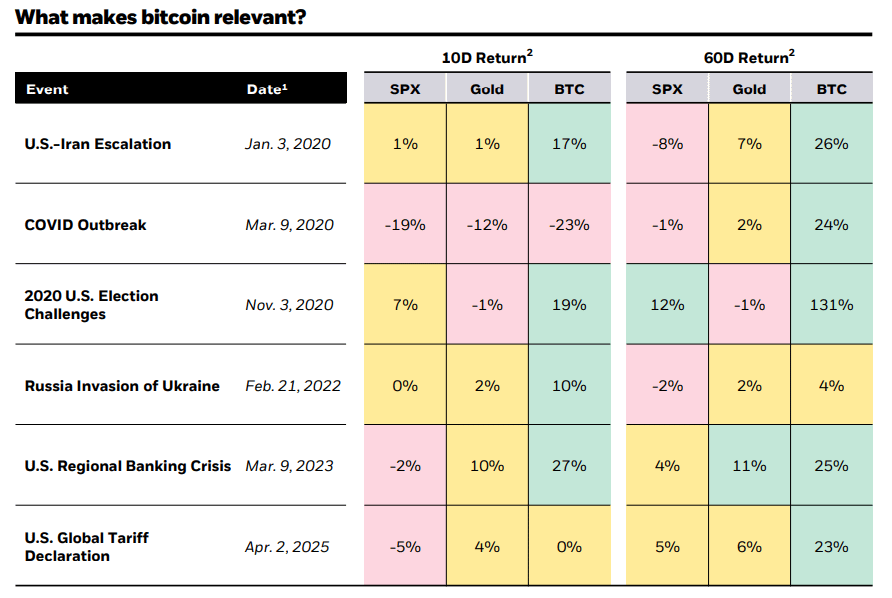
In addition to Fidelity’s report, BlackRock has also found that while Bitcoin tends to be highly volatile compared to other assets, Bitcoin price also tends to recover more sharply after volatile macroeconomic events compared to gold and the S&P 500. (Source: “Exploring Bitcoin as a Unique Diversifier”).
Ultimately, the real volatility emerges when we evaluate the volatility of other asset classes, including the U.S. dollar. When priced in Bitcoin, all of these asset classes are losing value quickly. Using a website such as pricedinbitcoin21.com, it’s possible to track how much value each of these assets have lost in Bitcoin terms. For example, the US dollar itself is down 83% over a 5-year timeframe against Bitcoin at the time of writing. The S&P 500 is down 68% and a new house is down 87%, again when both are priced against Bitcoin. When Bitcoin is the standard by which we value assets, those assets become cheaper as Bitcoin remains constant.
Bottom line: Despite it’s US Dollar-priced volatility, Bitcoin has proven over the last 17 years that it is a superior long-term asset to hold. If, as a business, you anticipate short term cash needs, then holding a large percentage of cash in Bitcoin may present some risk to your operating business. This can be be addressed with a much smaller allocation size.
“Bitcoin doesn’t produce cashflows. I can't really use it for anything.”
First, you can use Bitcoin in multiple ways, not least of which is preserving the value of your assets over long durations. You can also process payments in Bitcoin if you take payments through Square as of November 2025 (read our article on the tax treatment for Bitcoin transactions). Just because you cannot use your Bitcoin for anything physical, doesn’t mean that it there isn’t a use case.
Second, the objection that “Bitcoin doesn’t produce cashflows” misunderstands the fundamental nature of Bitcoin as a monetary asset. As a point of comparison, gold doesn’t produce cashflows, yet it has been valuable for thousands of years. Bitcoin’s value proposition lies in its scarcity, security, finality of settlement and utility as a decentralized, censorship-resistant form of money.
Moreover, Bitcoin’s lack of yield is a feature, not a bug, in an era of counterparty risk. Investors traditionally earn yield by taking risk, such as default risk in bonds, management risk in equities, or tenant risk in real estate. Bitcoin sidesteps these risks by offering self-sovereign ownership of an asset that cannot be debased with superior monetary properties to any other form of money. Its strength lies in its design with fixed supply, verifiable scarcity, and resistance to debasement. While cashflow is essential for a business, the fact that Bitcoin inherently lacks cashflow is not a reason to dismiss or ignore it.
“What’s even the accounting standard for holding Bitcoin?”
On the one hand, the accounting rules for holding Bitcoin on the balance sheet are simple, but on the other, it’s not. If, as a business, your company simply buys Bitcoin and records it as an asset on the balance sheet, it functions just like other assets that you’d list on your balance sheet and counts toward the assets you list before liabilities and shareholder equity.
On the other hand, it is essential to track cost basis, purchase dates, and monitor transactions. Furthermore, in 2023, the Financial Accounting Standards Board (FASB) updated U.S. GAAP rules for how businesses account for Bitcoin and other crypto assets. Previously, companies had to use a conservative “impairment-only” model that allowed them to record losses if Bitcoin’s value dropped. This same rule never allowed companies to reflect Bitcoin gains unless they sold it. This created a distorted picture of Bitcoin’s true value on the balance sheet. Under the new rules (ASU 2023-08), which apply to all companies using U.S. GAAP, Bitcoin must now be measured at fair market value each quarter, with gains and losses recorded directly in the income statement. This shift offers a more accurate and transparent view of a company’s financial position and allows unrealized gains to be reflected in reported earnings.
This change is helpful for business owners and entrepreneurs considering Bitcoin as a treasury asset. With fair value accounting, the upside of holding Bitcoin is no longer hidden. It can positively impact reported income, investor confidence, and capital strategy. It also sends a strong message to stakeholders that your company is forward-thinking and financially savvy in a world where digital assets are becoming more mainstream. However, it also means business leaders need proper accounting controls and valuation procedures in place. As the financial system continues to digitize, holding Bitcoin on your balance sheet isn’t just viable—it’s now fully compatible with modern accounting standards.
Bottom line: if your business holds or is considering holding Bitcoin, working with an accounting professional who understands both Bitcoin and current rules/laws should be an important consideration.
“I’ve heard that Bitcoin custody is complicated and risky. Seems too hard.”
In 2025, there are many solutions for businesses to custody their Bitcoin. While there are varying tradeoffs, the landscape of custodial solutions for Bitcoiners continues to evolve significantly.
There’s probably no better resource to understand the current landscape of Bitcoin custodial solutions than Bitcoin Park’s white paper on “Bitcoin Custody in 2025” by Rob Warren. Rob highlights how there are now three custodial strategies for holding and securing Bitcoin: single-signature self-custody, multi-signature self custody, and full custodial solutions. The paper neatly summarizes these three approaches as follows:
“Single-Sig Self-Custody—the user alone holds one key, which allows for full control over funds and a high degree of privacy, while demanding immense responsibility over personal security.”
“Multi-Sig Collaborative Custody—two or more keys spread across people, devices, or institutions, which allow for collaborative or multi-institutional responsibility over signing rights. Self custody multi-sig is absolutely possible and highly protective, but is technically beyond the scope of most Bitcoin users.”
“Fully Custodial—a third party holds 100% of keys. Often the first way participants engage with bitcoin, fully custodial solutions are the least private solution and offer meaningfully less protection against rehypothecation [the reuse of customer assets by a custodian for its own lending or collateral purposes] with a focus on user convenience.”
As you continue to learn more about Bitcoin, you will learn more about the tradeoffs associated with each approach to custody, but for now start by internalizing these three approaches.
Bottom line: Custody is important to understand and develop a plan for, but it shouldn’t be the reason you decide to not expose your balance sheet to Bitcoin.
Plotting Your Course
Maybe you’re beginning to be convinced that Bitcoin is an asset you need to buy and add to your business. If that’s so, you’re heading in the right direction. Next, consider how you plan on using Bitcoin and if you have the capabilities in your organization to handle the accounting, bookkeeping, and tax issues related to Bitcoin. If not, that’s the least of your concerns. Our team at Satoshi Pacioli is committed to bridging the gap between traditional finance and Bitcoin and are well equipped to serve businesses looking to gain Bitcoin exposure. If you have questions, reach out to our team and we’d be happy to talk about your situation.
Michael Leonardi, CPA
🟠 If this content was helpful to you, please consider liking and sharing this article with anyone who may find it useful and subscribing for more updates from the Satoshi Pacioli team.
